
By a tech blogger who learned about insurance the hard way
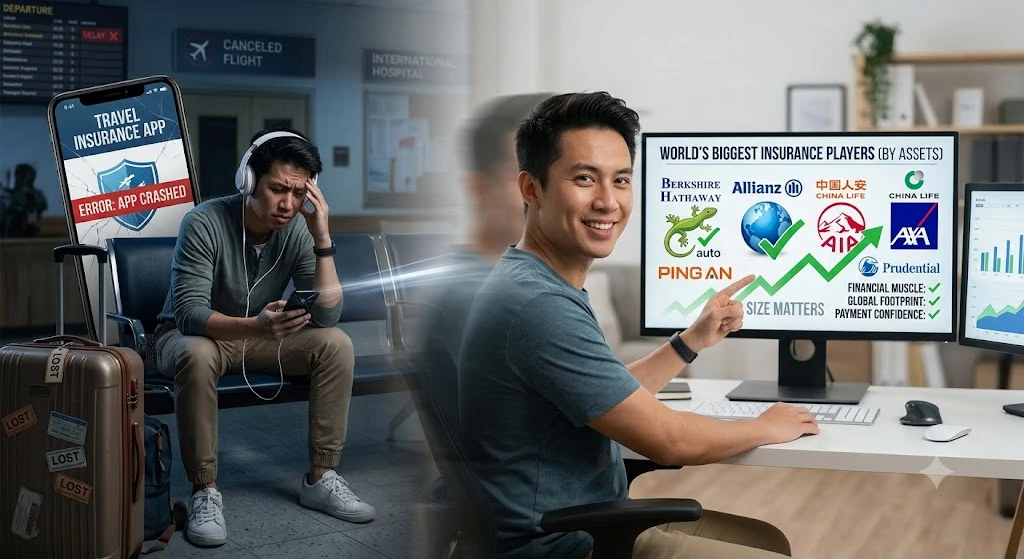
A few years back, I found myself sitting in a hospital waiting room in a foreign country, watching my travel insurance app crash every time I tried to file a claim. My luggage was lost, my connecting flight was cancelled, and the only thing standing between me and a $4,000 bill was a policy I’d bought from a company I’d never even heard of before.
That experience sent me down a rabbit hole I never expected. I started obsessing over which insurance companies actually have the financial muscle to pay out when things go wrong — not just the ones with flashy ads or catchy jingles.
So this article is the result of a lot of research, personal run-ins with insurance paperwork, and conversations with friends and colleagues across different countries. I’ve tried to break down the world’s biggest insurance players in a way that makes sense for regular people — not just finance nerds.
Let’s get into it.
Why the “Biggest” Insurer Matters More Than You Think
Here’s a mistake I made early on: I used to pick insurance based purely on price. The cheaper the premium, the better, right?
Wrong. Dead wrong.
What I learned — after that hospital trip and a few other unpleasant surprises — is that the financial size and global footprint of an insurer matters enormously. A company with $900 billion in assets isn’t just impressive on paper. It means they can actually pay you when the unthinkable happens, survive a massive natural disaster season, and still be around in 10 years when your life insurance policy matures.
Let me walk you through the ten companies that dominate this industry worldwide — and where each of them calls home.
1. Berkshire Hathaway — United States 🇺🇸
Assets: ~$948 billion | Revenue: ~$254 billion
If you know anything about Warren Buffett, you know Berkshire Hathaway. But most people don’t realize this conglomerate is actually the largest insurance company in the world by market cap — sitting at a jaw-dropping $663+ billion valuation.
The secret to Berkshire’s insurance dominance is something Buffett calls “float” — the gap between when policyholders pay premiums and when the company actually pays claims. Berkshire uses that float ($174 billion worth, as of 2025) as an interest-free loan to invest in things like stocks, railroads, and energy companies. It’s basically a financial superpower that no other insurer has been able to replicate.
Their insurance subsidiaries include:
- GEICO — One of the most recognized auto insurers in the US (you’ve definitely seen those gecko commercials)
- General Re — A reinsurance giant operating globally
- National Indemnity — Handles specialty and large-scale risks
Who it’s for: US residents looking for auto, property, and specialty insurance. Also great if you’re an investor who wants exposure to the insurance industry.
Lesson I learned here: GEICO’s online quote tool is genuinely fast and competitive. If you’re a US driver, it’s worth getting a quote even if you think you’re already getting a good rate elsewhere.
2. Allianz SE — Germany 🇩🇪
Assets: ~$1.05 trillion | Headquarters: Munich
Allianz is probably the most truly global insurer on this list. With a presence in over 70 countries, these guys are almost impossible to avoid if you’re traveling internationally or running a business with cross-border operations.
Founded in 1890, Allianz has had more than a century to build up its network. They’re especially strong in Europe but have significant operations in Asia, the Americas, and Africa.
What makes Allianz stand out is their range — they cover everything from your car and home to complex corporate liability risks and even art collections. They’re also the official insurance partner of major events like the Olympic Games, which gives you some sense of their scale.
Their asset management arm, PIMCO and Allianz Global Investors, manages money for pension funds and sovereign wealth funds worldwide.
Where they’re strongest: Germany, France, Italy, Spain, US, Brazil, China
Something I’ve noticed: Allianz’s mobile app in Europe is surprisingly good. Claims can be initiated digitally, and their customer service response times are better than you’d expect for a company this large.
3. Ping An Insurance Group — China 🇨🇳
Assets: ~$961 billion | Revenue: ~$156 billion | Headquarters: Shenzhen
Ping An is China’s largest private-sector financial conglomerate, and it’s arguably the most technologically sophisticated insurer on this entire list. They were one of the first major insurers to go all-in on AI, facial recognition, and digital claims processing — back when most Western companies were still arguing about whether to make their websites mobile-friendly.
Founded in 1988, Ping An grew up during China’s economic boom, and their expansion has been relentless. They serve hundreds of millions of customers through subsidiaries like:
- Ping An Life — China’s largest life insurer
- Ping An Property & Casualty — Auto and home coverage
- Ping An Bank — Yes, they have a bank too
- Lufax — A fintech lending platform
What’s genuinely impressive is their AI-powered healthcare platform. Ping An’s “Good Doctor” app has over 400 million registered users and connects patients with doctors digitally — a model that insurance companies in other countries are still trying to figure out.
Who it’s for: Primarily mainland China, but they’re expanding in Southeast Asia, and their B2B services are used by insurers globally.
4. China Life Insurance Group — China 🇨🇳
Assets: ~$885 billion | Headquarters: Beijing
China Life is the second Chinese giant on this list, and while Ping An wins on tech innovation, China Life wins on sheer scale. They serve over 300 million policyholders — that’s roughly the entire population of the United States.
State-owned and backed by the Chinese government, China Life has an unmatched distribution network across China’s cities and rural provinces. They’ve also been expanding their digital capabilities, investing heavily in mobile apps and AI-powered customer service to compete with Ping An.
For anyone building a life insurance product for the Chinese market, China Life is the 800-pound gorilla you have to understand and sometimes partner with.
Quick note for non-Chinese readers: Unless you’re doing business in China or living there, you probably won’t interact with China Life directly. But their scale is a reminder of just how massive the Chinese insurance market has become.
5. AXA — France 🇫🇷
Assets: ~$713 billion | Headquarters: Paris
AXA is the insurance company I encountered most during my years traveling through Europe, and honestly? They’ve always impressed me with their consistency. Whether it was a travel policy in Spain or health coverage in Belgium, the claims process was clear and the documentation was available in multiple languages.
AXA operates in 57 countries and is one of the world’s largest asset managers alongside being a major insurer. They cover:
- Life and health insurance
- Property and casualty
- Corporate and commercial risks
- Investment products
Their XL brand handles large corporate and specialty risks — things like massive construction projects, offshore energy, and aviation insurance.
AXA has also been serious about sustainability, pledging to stop insuring coal mines and committing billions to green investments. If that kind of thing matters to your company’s ESG profile, AXA is worth exploring.
Best known for: France, UK (through AXA UK), Belgium, Germany, US (AXA XL), Japan, Hong Kong
6. Prudential Financial — United States 🇺🇸
Assets: Over $900 billion (including managed assets) | Headquarters: Newark, NJ
Here’s where it gets a little confusing for newcomers: there are actually two major insurance companies called Prudential. Prudential Financial is the US-based one, while Prudential PLC is a UK/Asia-focused company. Different companies, different markets.
Prudential Financial is primarily a life insurance and retirement services company. They manage enormous amounts of retirement assets through their PGIM investment management arm — over $1.5 trillion in assets under management. That makes them one of the biggest institutional investors in the world.
For regular Americans, Prudential is best known for:
- Life insurance policies (term, whole, and universal)
- Retirement and annuity products
- Group insurance for employers
Real-life scenario: If your employer offers a group life insurance plan through work, there’s a solid chance it’s underwritten or managed by Prudential. They’re deeply embedded in the corporate benefits landscape.
7. MetLife — United States 🇺🇸
Assets: Roughly $700+ billion | Headquarters: New York City
MetLife has been around since 1868. Yes, 1868 — that’s before the telephone was invented. They’ve survived the Civil War, both World Wars, the Great Depression, and a dozen financial crises, which tells you something about their institutional resilience.
MetLife serves 90 million customers in over 40 countries and is particularly strong in:
- Group benefits for employers (dental, vision, disability)
- Life insurance
- Retirement products
- Pet insurance (yes, really — through PetFirst)
Their global operations are split between a US-focused entity and a more Asia/Europe-focused international arm. If you’re an expat or work for a multinational corporation, there’s a decent chance you’ve had MetLife coverage at some point.
One thing I appreciate about MetLife is their digital ecosystem. The MyBenefits app they use for corporate clients is actually one of the better HR/insurance platforms I’ve used — easy to navigate, fast to file claims, and reasonably good customer support.
8. Munich Re — Germany 🇩🇪
Assets: ~$310 billion | Headquarters: Munich
Munich Re is a different kind of company from the others on this list. They’re primarily a reinsurer — which means they insure other insurance companies. Think of them as the insurance industry’s insurance company.
Founded in 1880, Munich Re is one of the oldest and most respected names in global risk management. When a mega-hurricane hits the Gulf Coast, or an earthquake devastates an Asian city, Munich Re is often absorbing a massive chunk of the financial loss through the reinsurance contracts they’ve signed with local insurers.
They also operate in the primary insurance market through their ERGO brand, which sells directly to consumers in Germany and parts of Europe.
Why this matters to you: If you’re wondering why your home insurance still pays out even when a major catastrophe hits an entire region simultaneously — Munich Re (and companies like them) are a big part of why the insurance ecosystem can absorb those shocks.
9. Zurich Insurance Group — Switzerland 🇨🇭
Assets: ~$400 billion | Headquarters: Zurich
Zurich is one of those companies that’s been quietly dominant for decades without getting a lot of headlines. They’ve been in business since 1872 and operate in 170+ countries, serving both individuals and massive multinational corporations.
What Zurich is particularly good at is commercial insurance — protecting businesses against complex, multi-jurisdictional risks. If you run a company that operates in multiple countries, Zurich’s global programs (where one policy covers your operations in 20 different markets) are genuinely useful.
For individual customers, they’re strong in:
- Home and auto insurance (especially in Europe and North America)
- Life and disability coverage
- Travel insurance through their Cover-More brand
Countries where Zurich is especially prominent: Switzerland (obviously), Germany, UK, US, Latin America, and increasingly Southeast Asia
10. AIA Group — Hong Kong / Asia 🇭🇰
Assets: ~$340 billion | Headquarters: Hong Kong
AIA deserves a spot on this list because it dominates a geography that often gets overlooked in Western-centric rankings: Asia-Pacific. AIA is the largest independent, publicly listed pan-Asian life insurer, operating in 18 markets across the continent.
AIA traces its roots back to 1919 Shanghai. They focus almost exclusively on life and health insurance, and their understanding of Asia’s diverse regulatory environments and consumer needs is unmatched.
Markets where AIA is a dominant force:
- Thailand — Market leader in life insurance
- Hong Kong — One of the top players
- Singapore — Strong presence
- Malaysia, Philippines, Indonesia — Growing rapidly
- China — Operating through a licensed subsidiary
- India — Partnership with Tata Group (Tata AIA Life)
If you live in or work with Southeast Asia, understanding AIA is essential. Their financial advisors are everywhere, and their policy products are generally competitive.
Country-by-Country Quick Reference
Here’s a fast cheat sheet in case you want to find the dominant insurer by region:
| Country | Top Insurance Company |
|---|---|
| 🇺🇸 USA | Berkshire Hathaway, Prudential Financial, MetLife, State Farm |
| 🇩🇪 Germany | Allianz SE, Munich Re |
| 🇨🇳 China | Ping An Insurance, China Life Insurance |
| 🇫🇷 France | AXA |
| 🇨🇭 Switzerland | Zurich Insurance Group |
| 🇬🇧 UK | Prudential PLC, Legal & General, Aviva |
| 🇯🇵 Japan | Nippon Life, Japan Post Insurance, Tokio Marine |
| 🇮🇳 India | Life Insurance Corporation (LIC), Tata AIA, HDFC Life |
| 🇨🇦 Canada | Manulife Financial, Sun Life, Great-West Lifeco |
| 🇭🇰 Hong Kong / Asia-Pacific | AIA Group |
| 🇧🇷 Brazil | Porto Seguro, Bradesco Seguros |
| 🇦🇺 Australia | QBE, IAG, CommInsure |
The Biggest Mistakes People Make When Choosing an Insurer
After going through all of this research — and a few painful personal experiences — here are the traps I see people fall into most often:
Choosing only on price. A policy that’s $30 cheaper per month means nothing if the company denies your claim, drags out the process for months, or goes bankrupt during a major loss event.
Not checking financial strength ratings. Organizations like AM Best, S&P Global, and Moody’s rate insurance companies on their financial stability. Always look for at least an “A-” rating from AM Best before signing a long-term policy.
Ignoring the fine print on exclusions. I once had a travel policy that explicitly excluded “pre-existing conditions” — which, according to the fine print, included any condition mentioned in a doctor’s visit within the past 2 years. My mild asthma almost got my claim denied. Read. The. Exclusions.
Assuming a global brand means global coverage. Berkshire Hathaway is headquartered in the US, but their consumer policies (through GEICO, for example) are primarily for US customers. AXA operates in France but your AXA policy in France might not automatically work the same way as an AXA policy sold in Japan.
Not thinking about the claims process before you need it. Before you buy, spend 10 minutes Googling “[Company Name] claims experience” or “[Company Name] complaints.” Sites like the Better Business Bureau, Trustpilot, and Reddit’s r/personalfinance are full of real user experiences that paint a very different picture than the company’s marketing materials.
How to Pick the Right Insurer for Your Situation
Here’s a simple checklist I actually use:
- Define what you need to cover — Life, health, auto, property, travel, or business? Some companies specialize; others are generalists.
- Check if they operate in your country — Allianz might be the world’s biggest by assets, but if they’re not licensed in your market, that’s irrelevant.
- Look up their AM Best or S&P rating — You want at least “A-” for individual policies, “A” or better for long-term life insurance.
- Compare not just premiums but coverage limits and exclusions — Use tools like Policybazaar (India), CompareTheMarket (UK), or simply broker conversations for commercial insurance.
- Read recent reviews specifically about claims — This is where the truth lives. A company can have great premiums and terrible claims handling.
- Ask about digital capabilities — Can you file a claim through an app? Do they have 24/7 customer support? In 2025, there’s no excuse for an insurance company to not have a functional digital platform.
One Final Thing Worth Knowing
The global insurance market is projected to grow from about $8 trillion in 2024 to over $10.5 trillion by 2035. A huge chunk of that growth is coming from Asia — particularly China, India, and Southeast Asia — as the middle class expands and more people gain access to financial products.
Companies like Ping An and AIA are already positioning for that future. Meanwhile, insurtech startups (like Lemonade in the US, and ZhongAn in China) are disrupting the traditional model with AI-powered underwriting and instant digital claims.
The insurance industry isn’t glamorous. It’s not the kind of thing most people want to spend Saturday afternoons researching. But getting it right — picking a financially stable, globally recognized company with decent claims practices — is one of the most practical things you can do for your financial security.
I hope this breakdown saves you some of the headaches I went through learning this the hard way. And if you’re ever sitting in a foreign hospital waiting room watching an app crash, at least now you’ll know which companies have the balance sheets to actually back up their promises.
Sources: AM Best 2025 Rankings, S&P Global Market Intelligence 2025, beinsure.com, Insurance Business Magazine, Spherical Insights & Consulting. Data reflects 2024–2025 figures.
**Moon Awan** is the founder of MotoPolicy and a research-driven content creator focused on insurance and financial protection topics. With a strong background in building structured digital platforms, he specializes in analyzing and presenting complex insurance information in a clear and practical way.
At MotoPolicy, his work focuses on areas such as car insurance, health insurance, and policy comparison strategies. He continuously studies insurance trends, coverage structures, and pricing models to provide accurate and up-to-date insights that help readers make informed decisions.
His approach combines technical precision with in-depth research, ensuring that every article is well-organized, easy to understand, and useful for real-world applications.
Through MotoPolicy, his goal is to build a trusted resource where users can confidently learn about insurance, compare options, and improve their financial awareness.
While all content is carefully researched, readers are encouraged to consult licensed professionals for personalized insurance advice.



Can you tell us about the companies of india and UK