
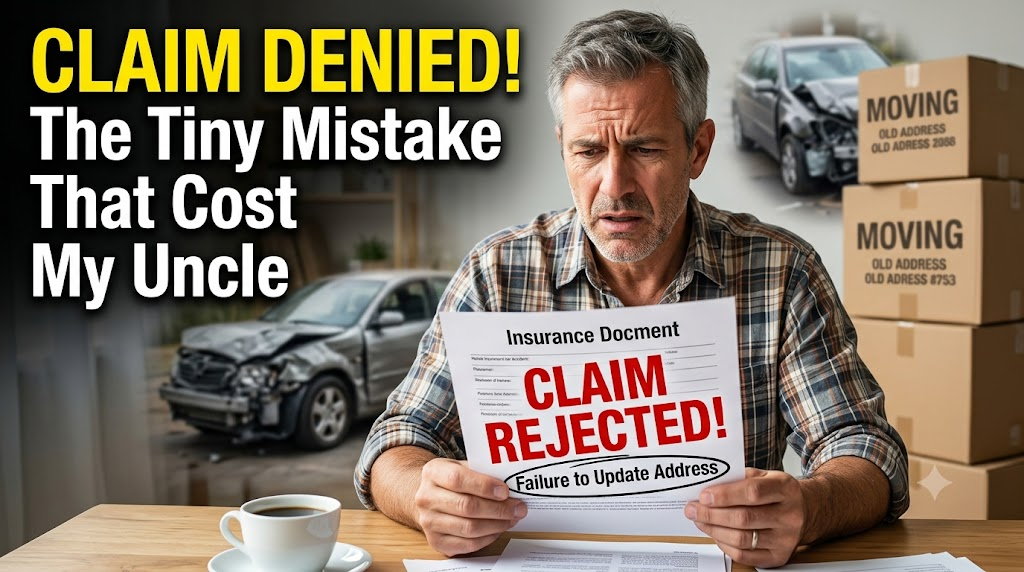
My uncle was in a car accident three years ago. Not his fault — a truck ran a red light and slammed into the driver’s side. He had full coverage, had been paying premiums for eleven years without ever filing a single claim, and thought he was completely protected.
His claim was rejected.
Not partially reduced. Not delayed. Fully rejected.
The reason? He had moved to a new apartment six months earlier and hadn’t updated his address with the insurance company. That one tiny administrative detail — something most of us wouldn’t even think twice about — gave the insurer grounds to deny the entire claim, arguing that “material information had changed” and he had failed to notify them.
He ended up spending eight months fighting that decision, hiring a lawyer, and eventually getting a partial settlement. But the damage — financially and emotionally — was done.
That story stuck with me. So I started paying closer attention, asking around, researching, and honestly, getting a little paranoid about my own policies. What I found was eye-opening.
Insurance companies aren’t necessarily evil (most of the time), but the claims process has a thousand tiny trapdoors that most people don’t know exist — until they fall through one.
Let me walk you through the most common and surprising reasons claims actually get rejected, with real situations I’ve come across or researched in depth.
The “Wrong Information at Signup” Trap
This one catches more people than anything else, and it’s sneaky because it often happens years before you ever file a claim.
When you apply for insurance — whether it’s health, auto, life, or home — you fill out a form. That form asks about pre-existing conditions, your driving history, the age of your roof, your smoking habits, your job. Most people answer these casually, sometimes guessing, sometimes rounding numbers, sometimes just not realizing what they’re omitting.
Insurance companies call this “misrepresentation,” and they take it extremely seriously.
Real case: A woman in her mid-40s was diagnosed with breast cancer. She had health insurance and expected it to cover her treatment. Except when she had originally applied, she mentioned she had seen a doctor “for a lump” two years earlier but hadn’t disclosed what the follow-up revealed. The insurer pulled her medical records during the claims review — something they’re allowed to do — found the omission, and denied her coverage on grounds of misrepresentation.
Now, she may not have deliberately lied. She may have forgotten. She may have thought it wasn’t important. None of that mattered legally.
What to do: When you fill out insurance applications, treat every question like it’s being asked by a lawyer. If you’re unsure whether something is relevant, disclose it anyway. It’s always better to have the insurer say “that doesn’t affect your rate” than to have them say “you failed to disclose this” years later.
Filing Too Late (The Deadline Nobody Reads)
There’s a window for filing claims. Not a generous, flexible window — a strict, contractual one. Miss it, and you may lose the right to claim entirely.
Most people don’t read the fine print on how long they have to report an incident. Some policies require you to notify them within 24 to 72 hours of an accident or incident. Life insurance claims sometimes have to be filed within 30 to 60 days of death. Home insurance policies often require you to take “immediate steps to prevent further damage” and report within a specific timeframe.
Real case: A homeowner had water damage from a roof leak. He patched the roof himself (because he thought he was handy) and waited three months to file a claim, figuring the indoor damage from mold and warped floors would be covered. The insurer denied it — first because the damage had worsened due to lack of prompt reporting, and second because the homeowner had “altered the damage site” by attempting repairs without insurer approval.
He lost approximately $18,000 in repairs he had to pay out of pocket.
What to do: The moment something happens — accident, theft, damage, death — contact your insurer. Even if you’re not sure you’ll file a claim. Just notify them. It costs nothing and protects your right to claim later.
The Exclusion Clause Nobody Warned You About
Every insurance policy has exclusions. These are things the policy specifically does NOT cover. The problem is, the exclusions section is usually buried in tiny print at the back of a 40-page document most people never read.
Things that commonly get excluded that people don’t expect:
Home insurance often excludes damage caused by “wear and tear,” “neglect,” or “gradual deterioration.” So if your pipes burst because they were old and corroded, and you hadn’t maintained them? Denied.
Health insurance frequently excludes “cosmetic procedures” — but what counts as cosmetic can be debated. A reconstructive procedure after an accident might get categorized as cosmetic depending on how the doctor codes it.
Travel insurance usually excludes pre-existing conditions — including conditions you didn’t know you had. If you get sick abroad and it turns out the cause was a condition you were “unaware of” but that showed signs in medical records, it may be excluded.
Life insurance almost universally excludes death by suicide within the first two years of the policy. This is widely known in the industry but rarely communicated clearly to buyers.
Real case: A man died in what his family described as an accident. But the life insurer hired an investigator who found evidence suggesting it may have been intentional, and denied the claim citing the suicide exclusion. The family contested, spent years in legal dispute, and eventually received a reduced settlement when they proved the death was accidental.
What to do: Before you buy any policy, ask your broker to walk you through every major exclusion. Specifically ask: “What are the top five reasons a claim on this policy would be denied?” Any good broker will be able to answer that question clearly. If they can’t, find a different broker.
Claiming for Something You Didn’t Actually Have Coverage For
This sounds obvious, but it happens constantly — and it’s not always the policyholder’s fault.
Sometimes people misunderstand what a policy covers. They were sold a product that was misrepresented. Sometimes they upgraded their home or possessions but never updated their coverage to match.
Real case: A freelance photographer had her camera equipment stolen from her car. She filed a claim under her renter’s insurance. The insurer denied it. Her renter’s insurance covered personal possessions, but her camera gear — worth over $8,000 — was used for business purposes. Business equipment used for income generation typically requires a separate business rider or commercial policy. Her standard renter’s policy explicitly excluded “business equipment.”
She had no idea. Nobody told her. She had simply assumed her cameras were covered the same as her laptop and TV.
What to do: If you work from home, have expensive equipment, or run any kind of freelance or side business, call your insurer and specifically ask about business equipment coverage. Also, if you’ve bought expensive items — jewelry, electronics, musical instruments, sports gear — check whether your policy covers them at full replacement value or whether there are per-item limits.
The “Drunk or Under the Influence” Instant Denial
Most people know that driving drunk means your auto insurer can deny a claim. What they don’t know is how broadly this gets applied.
If you’re in an accident and there’s any alcohol in your system — even below the legal limit in some jurisdictions and depending on how your policy is worded — your insurer may use it as grounds to deny or reduce your claim.
This also applies to other scenarios. If you injure yourself while intoxicated and file a health or accident claim, many policies include language about “self-inflicted injury while impaired” that can be invoked.
Real case: A man fell off a deck at a party and broke his arm. He had personal accident insurance. When he filed the claim, the insurer noted from hospital records that his blood alcohol was 0.07 — below the legal driving limit, but present. The insurer denied the claim citing an “impairment clause” in the policy. He had no idea that clause existed or that any alcohol in his system could be a factor.
What to do: Read the impairment and substance use clauses in your policy. They vary significantly. If you have activities-based insurance — travel, sports, adventure — these clauses tend to be stricter.
The Concurrent Cause Problem (Flood + Wind = Headache)
This one is particularly relevant for home insurance and is a genuine nightmare to deal with.
When a storm damages your home, it might be a combination of wind and rain and flooding. Wind damage might be covered. Flood damage might not be (unless you have separate flood insurance). If the insurer can argue that the uncovered cause — flood — contributed to or caused the damage, they may deny the entire claim, even for the wind portion.
This is called the “concurrent causation” problem, and courts in different states have ruled very differently on it.
Real case: During a major hurricane, a homeowner’s roof was damaged by wind (covered) and then interior flooding occurred (not covered, because they had no flood rider). The insurer argued they couldn’t separate the wind damage from the flood damage and denied everything. The homeowner hired a structural engineer to document which damage was wind-caused. After two years of dispute and legal fees, they recovered about 60% of their original claim.
What to do: In flood- and hurricane-prone areas, have separate flood insurance. After any storm, document everything with photos and video immediately. Get an independent adjuster or engineer’s assessment before the insurer sends their own adjuster. Having that documentation makes a massive difference if the claim is disputed.
The “No Police Report” Problem
For theft, vandalism, and certain accidents, insurance companies often require a police report as part of the claim documentation. No report? Denied or significantly delayed.
This seems obvious in retrospect, but many people don’t file police reports for minor thefts because it feels pointless (“the police won’t find my stolen bike anyway”). But that report is what proves to the insurer that the incident actually happened.
Real case: A woman had her car broken into in a parking garage. Her laptop, handbag, and about $600 in cash were stolen. She didn’t file a police report because she assumed nothing would come of it. When she filed an auto and renter’s insurance claim, the lack of a police report meant her cash claim was automatically denied (cash is rarely covered anyway, but that’s a separate issue) and her property claim required extensive documentation she didn’t have to support it.
What to do: File a police report for any theft or vandalism, no matter how minor. Do it online if your local department allows it — it takes ten minutes and protects you later. Keep the case number.
Policy Lapse: The Silent Killer of Claims
Missing a premium payment can lapse your policy. And if something happens while your policy has lapsed — even by a day — your claim will be denied.
This sounds simple, but it gets complicated with auto-pay failures, expired credit cards, billing address changes, and bank transitions. Many people genuinely don’t realize their policy has lapsed until they need to make a claim.
Real case: A family’s home was burglarized. They filed a claim, only to discover their homeowner’s insurance had lapsed three months earlier. Their credit card had been replaced after a fraud incident, and the auto-payment had failed. The insurer had sent notices — to an email address the family no longer monitored — and after a 30-day grace period, the policy was cancelled.
They were uninsured without knowing it.
What to do: Set a calendar reminder to check your insurance payment history every quarter. Make sure your insurer has a current email and phone number for billing alerts. If you change cards or banks, update your insurance payment details immediately — the same day.
When the Doctor Isn’t “In-Network” (Health Insurance Trap)
For health insurance, one of the most common and infuriating claim rejections comes from receiving care from an out-of-network provider — sometimes without knowing it.
You go to an in-network hospital. Your surgeon is in-network. But the anesthesiologist who shows up is out-of-network. You had no say in choosing them. You didn’t even know who they were until you got a bill months later.
This is called “balance billing” or the “surprise billing” problem, and it has ruined people financially even when they thought they did everything right.
Real case: A man had a scheduled surgery at an approved in-network hospital. He verified his surgeon was in-network. He did everything correctly. But during the procedure, an out-of-network assistant surgeon was brought in by his primary surgeon. The assistant’s fees — $12,000 — were not covered by insurance. The man had no knowledge this person had been involved until he received a collections notice.
Legislation like the No Surprises Act in the US has helped reduce this problem since 2022, but it still happens and in many cases is still contested.
What to do: Before any scheduled procedure, ask your hospital in writing: “Will all providers involved in my care be in-network with [your insurance]?” Get the answer in writing. Check your insurer’s provider directory yourself. And know your rights under applicable surprise billing laws in your region.
Common Mistakes That Get Claims Rejected — A Quick Reference
These are the smaller errors that combine with the bigger issues above to get claims denied:
Not documenting the original value of possessions. If you claim for stolen jewelry and can’t prove what you paid for it, the insurer will decide the value — and it won’t be in your favor. Keep receipts, photos, and appraisals of valuable items in cloud storage (Google Drive, Dropbox) or a safe deposit box.
Throwing away damaged items before the adjuster sees them. Many people clean up after a flood, fire, or storm before the insurance adjuster visits. This destroys evidence. Leave everything as-is, document it all yourself, and wait for the adjuster.
Guessing on claim amounts instead of documenting. Be precise. Use actual receipts, repair quotes from contractors, and original purchase prices. Inflating a claim — even unintentionally — can trigger a fraud investigation.
Not following up in writing. Every phone call you make to your insurer should be followed up with an email or letter summarizing what was discussed and agreed. “I spoke to John in claims on June 3rd and he confirmed…” creates a paper trail. Verbal agreements mean nothing in insurance disputes.
Signing releases too quickly. Insurers sometimes offer quick, low settlements right after an incident. Signing a release means you accept that amount as final. Never sign a release without consulting a lawyer or at minimum doing your own research on whether the offer is fair.
If Your Claim Gets Rejected, Here’s What to Actually Do
Rejection is not always final. Here’s the process worth following:
Step 1: Get the rejection in writing if you don’t already have it. You need to know the specific reason — in precise legal language — before you can challenge it.
Step 2: Re-read your policy in full, specifically the section related to your claim type. Sometimes adjusters make errors. The rejection reason may not actually align with your policy terms.
Step 3: File a formal written appeal with your insurer. Most insurers are legally required to have an internal appeal process. Submit additional documentation that addresses the specific rejection reason.
Step 4: If the internal appeal fails, file a complaint with your state or regional insurance regulatory authority. In the US, every state has an Insurance Commissioner’s office. In the UK, it’s the Financial Ombudsman Service. These bodies have real authority and insurers take their inquiries seriously.
Step 5: If the amount is significant — generally over $5,000 — consult a public adjuster or an attorney who specializes in insurance disputes. Many work on contingency, meaning they only get paid if you win.
The Bigger Picture Here
Insurance is supposed to be a safety net. But the way most people interact with it — buying it, setting it, and forgetting it — leaves them extremely vulnerable when something goes wrong.
The policyholders who get their claims paid tend to have a few things in common: they read their policies (at least the key sections), they communicate with their insurer proactively when anything changes, they document everything obsessively, and they push back when they believe a rejection is wrong.
The people who lose? They assumed they were covered and figured it would all work out. Sometime didn’t keep records. They signed whatever was put in front of them.
My uncle eventually got a partial payout after eight months of appeals. He also switched insurers, changed all his auto-billing to an account he monitors closely, updated every document the moment he moved, and now photographs every vehicle he drives for existing damage before he even starts the engine.
It took a painful experience to make him that careful. Hopefully you don’t need one of your own.
**Moon Awan** is the founder of MotoPolicy and a research-driven content creator focused on insurance and financial protection topics. With a strong background in building structured digital platforms, he specializes in analyzing and presenting complex insurance information in a clear and practical way.
At MotoPolicy, his work focuses on areas such as car insurance, health insurance, and policy comparison strategies. He continuously studies insurance trends, coverage structures, and pricing models to provide accurate and up-to-date insights that help readers make informed decisions.
His approach combines technical precision with in-depth research, ensuring that every article is well-organized, easy to understand, and useful for real-world applications.
Through MotoPolicy, his goal is to build a trusted resource where users can confidently learn about insurance, compare options, and improve their financial awareness.
While all content is carefully researched, readers are encouraged to consult licensed professionals for personalized insurance advice.


