
I still remember the exact moment I realized I’d been completely wrong about insurance.
It was a Tuesday afternoon. I was 23, freshly employed, and my manager handed me a stack of enrollment forms for the company’s benefits package. Health insurance. Dental. Life insurance. Short-term disability. Long-term disability.
I stared at the stack for a full minute. Then I did what most young people do — I picked the cheapest health plan, skipped everything else, and went back to my desk thinking I’d “figure it out later.”
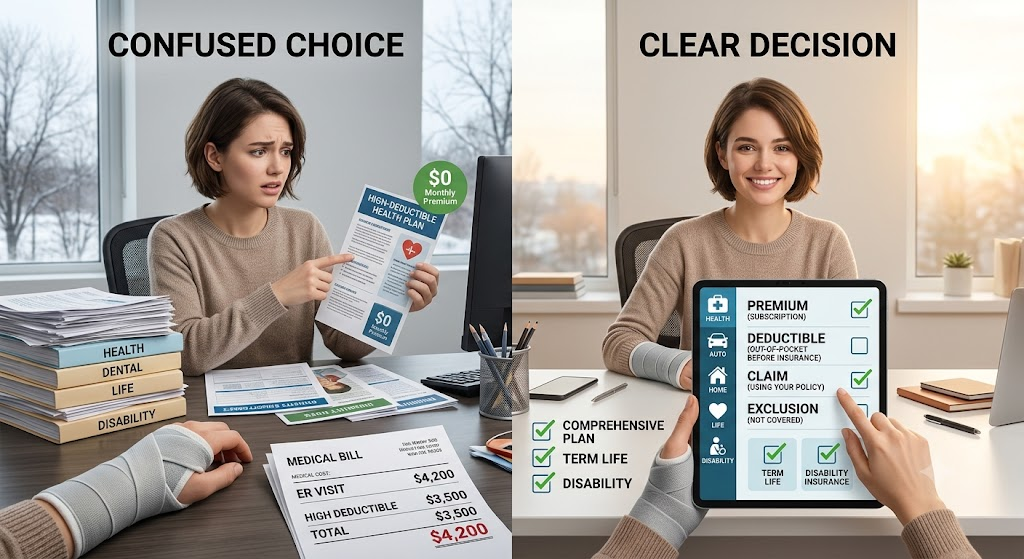
Three months later, I slipped on ice in a parking lot and fractured my wrist. The ER visit alone cost $4,200. My cheap insurance plan had a $3,500 deductible. I ended up paying almost the entire bill out of pocket.
That was my expensive education on what insurance actually means — and more importantly, what happens when you don’t understand it.
This article is what I wish someone had explained to me before that parking lot moment. No complicated jargon. No fine print. Just a real explanation of what insurance is, how it works, and how to stop making the mistakes I made.
So, What Exactly Is Insurance?
Here’s the simplest way I can explain it.
Imagine ten of your friends each put $100 into a shared pot every month. That’s $1,000 total. Now, if one of those friends gets into a car accident and needs $800 for repairs, they pull from that shared pot instead of paying out of their own pocket. The rest of you only lost $100 each, but your friend didn’t get wiped out by an unexpected $800 expense.
That’s insurance at its core. It’s a risk-sharing system.
In real life, instead of ten friends, you have thousands — sometimes millions — of people contributing money (called premiums) to a pool managed by an insurance company. When something bad happens to one of those people — a car accident, a house fire, a medical emergency — the company pays out from that pool.
The insurance company’s job is essentially to calculate risk. They study huge amounts of data to figure out: How often do these events happen? How much do they cost? How much does everyone need to chip in so the pool never runs dry?
When it works well, it’s one of the most important financial tools a person can have. When you don’t understand it, it’s just a monthly bill that feels like it disappears into thin air.
The Words You’ll Keep Seeing (Explained Like You’re a Human)
Before anything else, let’s kill the jargon. These are the five terms that show up in almost every insurance policy, and they tripped me up constantly in the beginning.
Premium This is what you pay regularly — usually monthly — to keep your insurance active. Think of it like a subscription fee. Even if nothing bad happens to you, you still pay this.
Deductible This is the amount you pay out of your own pocket before your insurance kicks in. So if you have a $1,000 deductible and get a $3,000 medical bill, you pay the first $1,000 and insurance covers the rest. This is the number I completely ignored when I picked my cheap plan. Don’t be me.
Premium vs. Deductible trade-off: Generally, a lower monthly premium means a higher deductible. A higher premium usually means a lower deductible. If you’re young and healthy and never use insurance, a high deductible plan saves you money. If you know you’ll need regular care, a lower deductible plan often makes more sense.
Coverage Limit This is the maximum amount your insurance will pay. After this cap is hit, you’re on your own. Some health plans in the US have out-of-pocket maximums — after which they cover 100%. Always know your limits.
Claim A claim is when you formally ask your insurance company to pay for something. You get in a car accident? You file a claim. You have a hospital stay? You file a claim. It’s the process of actually using your insurance.
Exclusion This is what your insurance does not cover. Every policy has exclusions. Flood insurance typically doesn’t come with your standard homeowner’s policy, for example. Many people find this out after a flood destroys their house — one of the most gut-wrenching discoveries in personal finance.
The Main Types of Insurance (And Why They Each Matter)
There are dozens of types of insurance out there, but these are the ones that affect most people at some point in their lives.
1. Health Insurance
This one hits closest to home — literally. Medical costs are one of the leading causes of financial hardship around the world. A single night in a hospital in the US can cost upwards of $10,000. Without insurance, a serious illness can wipe out savings that took a decade to build.
Health insurance covers doctor visits, hospital stays, surgeries, prescriptions, mental health care, and sometimes vision and dental (though those are often separate). In countries with universal healthcare, this is handled by the government. In others like the US, you either get it through an employer, buy it yourself, or rely on government programs like Medicaid or Medicare.
The thing nobody tells you about health insurance: using it feels weirdly complicated at first. You’ll hear terms like co-pay (a flat fee you pay for a visit), co-insurance (a percentage you pay after your deductible), in-network vs. out-of-network (whether your doctor has a deal with your insurer), and prior authorization (when your insurance has to approve a treatment before you get it).
It’s a lot. But the more you engage with it, the less scary it gets.
2. Auto/Car Insurance
If you drive a car, this one is usually not optional — it’s legally required in most countries and states. Auto insurance covers damage to your car, damage you cause to other people’s cars, and injuries from accidents.
There are a few layers here. Liability insurance covers damage you cause to others. Collision insurance covers damage to your own car in a crash. Comprehensive insurance covers everything else — theft, vandalism, natural disasters, a deer jumping out of nowhere at 2am (yes, this happens).
A mistake I see a lot: people skimp on liability coverage to save on premiums. But liability is the most important part. If you cause a serious accident and someone gets injured, the medical bills can reach hundreds of thousands of dollars. Without adequate liability coverage, you’d be personally responsible for that.
3. Homeowner’s or Renter’s Insurance
If you own a home, homeowner’s insurance protects the building itself and your belongings. If you rent, renter’s insurance only covers your personal belongings — not the structure (that’s the landlord’s problem).
Here’s something that genuinely surprised me: renter’s insurance is cheap. I’ve seen policies for $10-$15 per month. Yet a huge percentage of renters skip it. Then their laptop gets stolen or a kitchen fire ruins their furniture and clothes, and they have nothing to fall back on.
Homeowner’s insurance also usually covers liability — so if someone slips and falls on your property and sues you, you’re covered.
The big gap to know about: standard homeowner’s policies don’t cover floods or earthquakes. Those require separate policies, and they’re crucial depending on where you live.
4. Life Insurance
This one’s easier to explain with a question: If you died tomorrow, would the people who depend on you financially be okay?
Life insurance pays out a lump sum (called a death benefit) to your beneficiaries — usually a spouse, children, or other family members — when you die. It’s not really for you; it’s for the people who count on your income.
There are two main kinds. Term life insurance covers you for a set period (10, 20, 30 years) and pays out if you die within that term. It’s relatively affordable. Whole life insurance covers you for your entire life and has an investment component, but it’s much more expensive.
For most people, especially those in their 20s and 30s with young families, term life insurance is what makes sense. It’s straightforward, affordable, and provides real protection during the years when your family is most financially vulnerable.
5. Disability Insurance
Here’s the type most people never think about until it’s too late.
Disability insurance replaces a portion of your income if you become unable to work due to illness or injury. Think about how much of your financial life depends on your ability to show up and do your job. Now imagine that ability disappearing for six months, a year, or permanently.
A lot of employers offer short-term and long-term disability as part of a benefits package. If yours does, take it. If you’re self-employed or your employer doesn’t offer it, you can buy it privately. It’s genuinely one of the most underrated types of insurance out there.
How Does Insurance Actually Work? (The Real Process)
Let me walk you through what happens from the moment you buy a policy to the moment you actually use it.
Step 1: You apply for a policy. You give the insurance company information about yourself — your age, health history, driving record, whatever’s relevant to the type of insurance. They use this to figure out your risk level, which determines your premium.
Step 2: You pay your premium. Usually monthly, sometimes annually. This keeps your policy active. Miss payments, and your coverage can lapse — meaning you’re no longer covered.
Step 3: Something happens. Life throws a curveball. Car accident, medical issue, house damage — whatever it is, you’re now in a situation where you might need to use your insurance.
Step 4: You file a claim. You contact your insurance company and report the incident. This can be through a phone call, an app, or an online portal. You’ll often need to provide documentation — photos, medical records, repair estimates, a police report.
Step 5: The claim gets reviewed. An insurance adjuster — someone whose job is to assess claims — reviews your case. They determine whether it’s covered, and for how much. This process can take anywhere from a few days to several weeks depending on the complexity.
Step 6: You get paid (or not). If the claim is approved, the company pays out — either directly to you, or in some cases (like healthcare) directly to the provider. If it’s denied, you have the right to appeal.
The appeal process is something a lot of people don’t realize exists. If your claim gets denied, don’t just accept it. Read the denial reason carefully, gather any additional documentation, and push back. I’ve personally seen denied claims get reversed on appeal multiple times.
Common Mistakes People Make With Insurance
I’ve made some of these myself. Others I’ve watched family and friends learn the hard way.
Buying based only on price. The cheapest plan isn’t always the best plan. A policy with a tiny premium but a massive deductible and poor coverage could end up costing you far more than a slightly more expensive plan with real protection.
Not reading the exclusions. This is where people get blindsided. “Oh, that’s not covered” is one of the worst sentences you can hear during an already stressful event. Read what your policy doesn’t cover before you need it.
Underinsuring your home. A lot of homeowners insure their house for what they paid for it, not what it would cost to rebuild it. Construction costs change. Always check that your coverage reflects current rebuild costs.
Letting a policy lapse. Missing a payment and losing coverage — then getting sick or having an accident during the gap — is a nightmare scenario that’s entirely avoidable with auto-pay.
Not updating beneficiaries. Life changes. People get married, divorced, have kids. If you haven’t updated who receives your life insurance payout, an ex-spouse might still be listed. Check this periodically.
Assuming employer coverage is enough. Employer-sponsored insurance is great, but it’s not always comprehensive. Know what your employer provides and plug any gaps yourself.
A Few Tools That Actually Help
Managing insurance doesn’t have to be a paperwork nightmare. These tools have made it easier for me and people I know:
- Policygenius — A solid platform for comparing life, health, and disability insurance quotes across providers.
- Insurify — Good for comparing auto insurance specifically.
- Your insurer’s app — Most major insurance companies now have apps where you can file claims, upload photos, check your coverage, and contact support. State Farm, Geico, Allstate, and others all have functional apps worth downloading before you ever need them.
- A simple spreadsheet or notes file — Seriously underrated. Just keeping a document with your policy numbers, coverage limits, deductibles, and customer service numbers all in one place saves enormous headaches during a stressful moment.
A Note on Insurance in Pakistan and Other Markets
If you’re reading this from Pakistan (or other markets outside the US), the landscape looks a little different but the fundamentals are exactly the same.
In Pakistan, companies like State Life Insurance, Jubilee Life, Adamjee Insurance, and EFU Life are major players. Microinsurance products have also grown significantly, offering smaller, more affordable coverage to lower-income households. The concept of Takaful — a Shariah-compliant alternative to conventional insurance based on mutual contribution — is widely available and follows the same basic risk-pooling principle, just structured to avoid interest (riba) and uncertainty (gharar) in a way compliant with Islamic finance principles.
Whether you’re dealing with a conventional insurer or a Takaful operator, the questions to ask are the same: What does it cover? What are the exclusions? What’s the claim process? What’s the deductible or excess?
How to Actually Pick an Insurance Policy (Without Getting Overwhelmed)
If you’re starting from scratch, here’s a simple approach that works.
Start with the most important risks first. If you have people depending on your income, life insurance matters. If you drive a car, auto insurance isn’t optional. If you have significant health expenses, a good health plan is priority one.
Figure out your actual financial exposure. How much do you have in savings? If you have a solid emergency fund, you can tolerate a higher deductible (and pay a lower premium). If you’re living paycheck to paycheck, a lower deductible is worth the extra premium.
Get at least three quotes. Prices vary significantly between insurers for identical coverage. Never buy from the first place you look.
Ask the uncomfortable questions. How do I file a claim? What’s the average processing time? What reasons would lead to a denial? A good agent should answer all of these without getting defensive.
Read at least the summary of benefits. You don’t need to read a 60-page policy document cover to cover. But most insurers are required to provide a plain-language summary. Read that.
The Bigger Picture: Why Insurance Is Worth Taking Seriously
I want to be honest about something.
For most of my early adult life, I treated insurance like a necessary evil — a bill I paid but never thought about. That’s an easy trap to fall into when you’re young and healthy and nothing bad has happened yet.
But insurance isn’t really about what’s likely to happen. It’s about what you can afford to handle if it does happen.
Most of us can’t absorb a $50,000 hospital bill, a $30,000 car accident, or the financial impact of dying without income protection for our families. Insurance turns those catastrophic possibilities into manageable, predictable monthly expenses.
The people I’ve seen get into serious financial trouble almost always had two things in common: they underestimated risk, and they were underinsured. Those aren’t coincidences.
You don’t need to become an insurance expert. You just need to understand enough to make good decisions — and to stop picking the cheapest option without reading what it actually covers.
Wrist fracture, $4,200 bill, $3,500 deductible. That was my lesson.
Hopefully this article is yours — and it cost you nothing but a bit of reading time.
Have questions about a specific type of insurance or a situation you’re trying to figure out? Drop it in the comments — real questions get real answers.
Hi, I’m Dr. Robert Jr, the Co-founder and voice behind MotoPolicyHub on ifi.life.
With over 18 years in the insurance and healthcare industry, I’ve seen the good, the bad, and the downright ugly side of insurance policies. I started my career as a health policy analyst and later moved into insurance consulting, helping families and individuals navigate complex car and health insurance systems in both the United States and international markets (including Pakistan and Europe).
My journey into writing about insurance wasn’t planned — it came from painful personal lessons. I’ve been burned by hidden exclusions, surprise medical bills (like that $340 lab test I’ll never forget), and poorly chosen car insurance policies that left me exposed after accidents. I’ve watched friends and family struggle with denied claims, skyrocketing premiums, and confusing policy jargon. These real-life experiences taught me one clear truth: most people are one wrong policy choice away from financial stress.
Over the years, I’ve:
Advised hundreds of families on choosing the right health and auto insurance plans
Helped clients successfully file and win complex insurance claims
Analyzed thousands of policies across major providers
Worked with insurance brokers, hospitals, and regulatory bodies to understand what actually works in 2026
I hold a Doctorate in Healthcare Administration and have certifications in Risk Management and Insurance. But more importantly, I’ve lived the reality that I write about. Every article on this site comes from a genuine desire to help everyday people avoid the costly mistakes I and my loved ones have made.
At MotoPolicyHub, I don’t write dry, corporate insurance guides. I share straightforward, real-world advice in plain language — the kind I wish I had when I was younger and making my first big insurance decisions. Whether it’s choosing comprehensive vs third-party car insurance, understanding what your health plan actually covers, or finding the best family coverage without breaking the bank, my goal is simple: give you the knowledge and confidence to make smarter insurance choices.
I’m based between the United States and Pakistan, which gives me a unique perspective on both Western and emerging-market insurance systems. When I’m not researching policies or writing, you’ll find me spending time with my family, working on my classic cars, or learning new ways to simplify complicated financial topics.
Thank you for visiting MotoPolicyHub. If my articles help you save money, avoid stress, or finally understand your coverage — then I’ve done my job.
Welcome to the family.
Let’s make insurance less confusing, together.
— Dr. Robert Jr



Pingback: Insurance Terminology Explained: A Beginner’s Guide to Translating the Jargon - MotoPolicyHub
Pingback: The Ugly Truth About Insurance Fraud: How It Works - MotoPolicyHub
Pingback: Insurance Terminology Explained: A Beginner's Guide to the Words That Actually Cost (or Save) You Money - MotoPolicyHub