
Last spring, I sat on my couch with four browser tabs open, a lukewarm cup of tea, and a creeping sense that I was being ripped off.
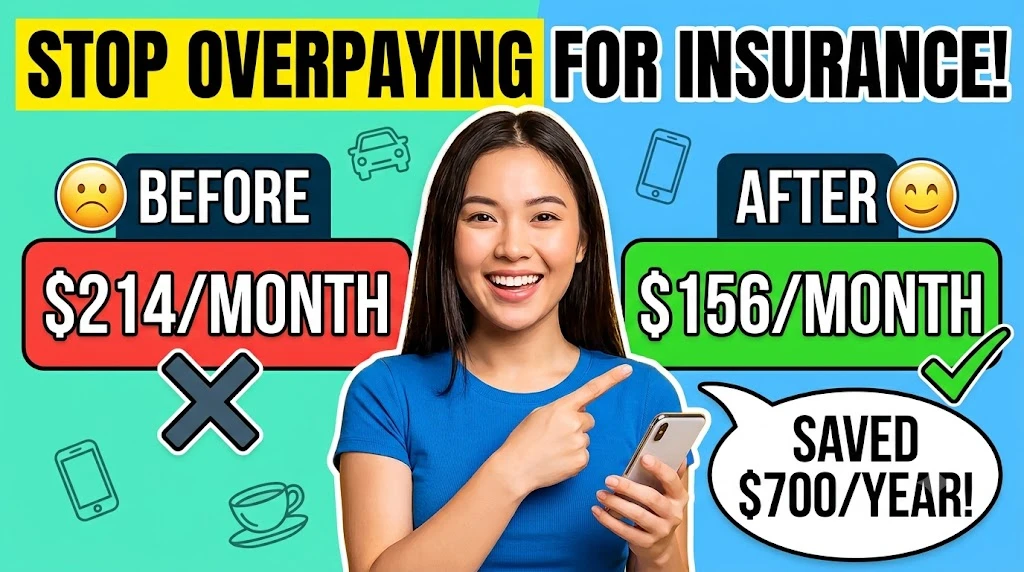
My car insurance had just renewed automatically — $214 a month — and I genuinely couldn’t remember the last time I’d actually shopped around. A friend mentioned offhand that she’d cut her rate nearly in half just by spending an afternoon comparing quotes online. Half. I brushed it off at the time. But that renewal notice was the wake-up call I needed.
What followed was a two-week deep dive into how insurance quotes actually work online, what the platforms don’t tell you, and why the “lowest quote” you see isn’t always the deal it looks like. Here’s everything I learned — including a few mistakes I made so you don’t have to.
Why Most People Overpay (And Keep Doing It)
The honest answer? Inertia.
Insurance companies know that most people auto-renew without checking. They count on it. Loyalty rarely gets you a lower rate — in fact, a phenomenon called price optimization means some insurers quietly raise rates for customers who haven’t shopped around recently, because the data suggests you probably won’t leave.
That’s not a conspiracy theory. It’s a documented pricing strategy. The Consumer Federation of America has published research on it, and several state insurance regulators have raised concerns about the practice.
The fix is annoyingly simple: get new quotes every year. Even if you end up staying with your current provider, knowing what competitors offer gives you real negotiating power.
The Difference Between Comparison Sites and Direct Quotes
This tripped me up early on. I assumed all “compare quotes” websites were the same. They’re not — and the difference matters.
Aggregator / Comparison Sites pull quotes from multiple insurers at once. You fill out one form and see several options side by side. Popular ones include:
- The Zebra — one of the most comprehensive for auto insurance in the US
- Policygenius — especially good for life, home, and health coverage
- NerdWallet’s Insurance Comparison Tool — helpful if you’re also managing other finances
- Compare.com — straightforward UI, good for quick auto quotes
- Insurify — AI-powered comparison tool that’s gotten noticeably smarter over the past couple of years
The catch with aggregators: not every insurer partners with every platform. Some major carriers — USAA, Erie Insurance, and occasionally Geico — don’t always show up in comparison results. So aggregators give you a fast overview, but they’re not exhaustive.
Direct Quote Sites are the insurers’ own websites. You go to Progressive, Allstate, or State Farm directly and get a quote from them alone. More steps, but sometimes you find deals that don’t appear on comparison sites, especially if the insurer is running a promotion or has a discount for direct customers.
My approach: Start with two or three aggregators to get a ballpark, then go direct to any insurer that looks competitive — and always check USAA directly if you or a family member has military connections (their rates are often dramatically lower).
Step-by-Step: How I Actually Got Better Quotes
Here’s the exact process I followed, refined after a few stumbles:
Step 1 — Gather Your Info Before You Start
Nothing kills momentum like stopping mid-form to hunt for details. Before opening a single quote site, have this ready:
- Driver’s license numbers for everyone on the policy
- Vehicle info: year, make, model, VIN (found on your dashboard or registration)
- Current policy details: coverage limits, deductibles, expiration date
- Annual mileage estimate (most people underestimate this — check your last oil change record)
- Any recent claims or violations — be honest, they’ll pull your record anyway
Step 2 — Start with The Zebra or Insurify
Both are fast, require minimal info upfront, and give you a real sense of the market rate for your situation. The Zebra is particularly good because it shows you quotes in real-time alongside a breakdown of what each covers.
Don’t just look at the monthly premium. Scroll down and compare:
- Liability limits (are they actually equivalent?)
- Comprehensive vs. collision coverage
- Deductible amounts
- Roadside assistance or rental reimbursement inclusions
A quote that looks $30/month cheaper might have a $1,500 deductible instead of $500. That’s not a deal — that’s a delayed expense.
Step 3 — Check Policygenius for Non-Auto Needs
If you need life, renters, or home insurance alongside auto, Policygenius is genuinely excellent. What I like is that they assign you an actual human advisor (no charge) who can walk you through confusing terms. I used their life insurance tool and got help understanding the difference between term and whole life without any hard sell.
Step 4 — Go Direct to the Top 3 Contenders
Once you have your shortlist from the aggregators, visit each insurer’s site directly. Sometimes you unlock:
- Multi-policy discounts (bundling auto + home)
- Pay-in-full discounts (paying annually vs. monthly)
- Telematics/usage-based discounts (I’ll cover this below)
- Professional or alumni association discounts that aren’t advertised on comparison sites
For big-name carriers, here are the direct quote pages:
Step 5 — Call Your Current Insurer Last
This is a tip I got from a friend who worked in insurance for years: don’t call your current provider first, asking for a better rate. Get real competing quotes first, then call and ask if they can match or beat the best one.
Retention departments have more pricing flexibility than new business agents. When I called mine and mentioned I had a quote from Progressive that was $47/month less for the same coverage, they found a loyalty discount that hadn’t been applied to my account. Funny how that works.
The Telematics Trap (And When It’s Actually Worth It)
Many insurers now offer usage-based insurance (UBI) — also called telematics — where you let them track your driving behavior through an app or a small plug-in device, in exchange for potential discounts.
Programs like:
- Geico DriveEasy
- Progressive Snapshot
- State Farm Drive Safe & Save
- Allstate Drivewise
…can save good drivers 10–30% on their premium.
I tried Progressive Snapshot. Here’s what I didn’t expect: the app also penalizes certain behaviors. Late-night driving (between midnight and 4am) flagged as higher risk, even if I was doing nothing wrong. If you’re someone who regularly works night shifts or drives during those hours, telematics might actually raise your rate.
Read the fine print on any UBI program. NerdWallet has a solid breakdown of the main programs and which driving habits they monitor.
What Affects Your Quote More Than You Think
People obsess over the wrong variables. Here are some factors that move the needle significantly — and that many people don’t realize they can influence:
Credit Score — In most US states, insurers use a version of your credit score (an “insurance score”) to set rates. Improving your credit can literally lower your insurance bill. Check your score for free through Credit Karma or Experian.
Deductible Choice — Raising your deductible from $250 to $1,000 can cut your premium noticeably. If you have an emergency fund to cover the gap, this is usually worth doing.
Coverage You Might Not Need — On an older car worth under $4,000, dropping comprehensive and collision and keeping only liability often makes financial sense. Use Kelley Blue Book to check your car’s actual value before deciding.
Your ZIP Code — Moving even a few miles can change your rate. I moved from one side of a city to another and saw a $22/month difference just from the new area’s theft and accident statistics.
Profession and Education — Some insurers offer discounts for teachers, nurses, military personnel, engineers, and others. It’s worth asking directly.
Common Mistakes That Cost People Money
I made a few of these myself:
Mistake 1: Comparing only the premium Monthly cost is just one number. Coverage limits and deductibles are what determine whether you’re actually protected. Always compare apples to apples.
Mistake 2: Assuming the name-brand insurer is always better Smaller regional carriers like Erie Insurance, Auto-Owners Insurance, and Amica consistently rank high for customer satisfaction in J.D. Power surveys — often beating the national giants. Don’t dismiss them.
Mistake 3: Not asking about every possible discount Insurers won’t always volunteer these. Ask specifically about: good student discount, multi-car discount, paperless billing discount, defensive driving course discount, and homeowner discount.
Mistake 4: Shopping only once Your rate isn’t permanent. Get new quotes when your car ages, your driving record improves, you move, you get married, or you simply haven’t checked in a while (annually is a good rhythm).
Mistake 5: Not reading reviews before signing Price matters, but so does claims experience. Check an insurer’s reviews on AM Best (for financial stability) and J.D. Power (for claims satisfaction) before committing.
A Quick Word on Health and Renters Insurance
Everything above applies most directly to auto insurance — but the same principles work for other types.
For health insurance, especially if you’re self-employed or between jobs, Healthcare.gov is the official marketplace. Depending on your income, you may qualify for subsidies that make coverage far more affordable than you’d expect.
For renters insurance, it’s one of the most underused products out there. The average policy runs $15–$30/month and covers your belongings if they’re stolen, damaged, or destroyed — including in situations like a neighbor’s fire spreading to your unit. Lemonade has made this space genuinely easy to navigate with a fully digital experience and fast claims handling. Worth checking even if you’ve never had renters insurance before.
For home insurance, Hippo and Kin are newer players that have modernized the quote process significantly, especially for homeowners in states like Florida and Texas where legacy insurers have pulled back.
The Actual Bottom Line
Getting a better insurance quote online isn’t complicated — but it does require you to actually do it, which most people put off indefinitely.
Here’s the condensed version of what I’d tell a friend:
- Set aside 90 minutes — that’s genuinely all it takes
- Start on The Zebra or Policygenius for a market overview
- Go direct to your top 2-3 contenders and ask about every discount
- Get your best competing quote in hand, then call your current insurer
- Do this every year — put a calendar reminder right now
After my two-week deep dive, I switched from my old provider to a regional carrier I’d never heard of before. Same coverage, better claims reputation, and $58 less per month. Over a year, that’s nearly $700 back in my pocket — for two hours of work.
The information to do this has always been available. The tools to do it quickly have never been better. The only thing that was ever stopping most of us was just… not starting.
Disclosure: Some links in this article may be affiliate links, meaning we may earn a small commission if you sign up through them — at no extra cost to you. We only link to platforms we’ve actually used or thoroughly researched.
**Moon Awan** is the founder of MotoPolicy and a research-driven content creator focused on insurance and financial protection topics. With a strong background in building structured digital platforms, he specializes in analyzing and presenting complex insurance information in a clear and practical way.
At MotoPolicy, his work focuses on areas such as car insurance, health insurance, and policy comparison strategies. He continuously studies insurance trends, coverage structures, and pricing models to provide accurate and up-to-date insights that help readers make informed decisions.
His approach combines technical precision with in-depth research, ensuring that every article is well-organized, easy to understand, and useful for real-world applications.
Through MotoPolicy, his goal is to build a trusted resource where users can confidently learn about insurance, compare options, and improve their financial awareness.
While all content is carefully researched, readers are encouraged to consult licensed professionals for personalized insurance advice.


